By: Marcy Paulson
A growing number of Americans are choosing between rent or insurance, groceries or prescriptions, the car payment or the deductible. Health coverage is supposed to reduce fear. For many families and individuals today, it provides a new source of fear, as even good plans can still leave people exposed.
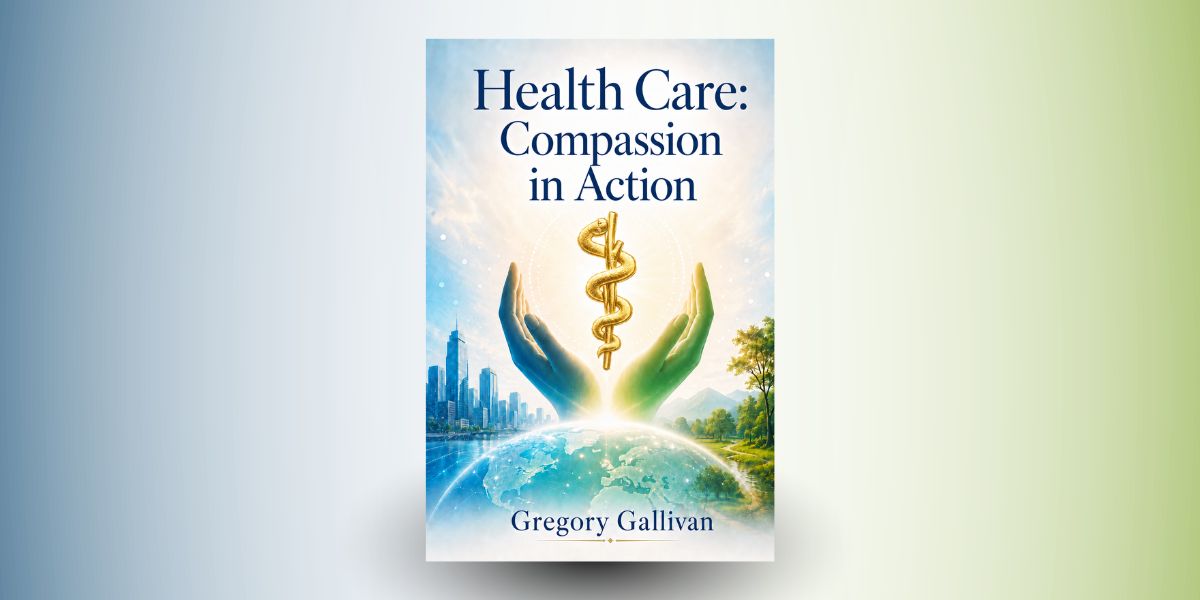
In his newly released book, “Healthcare: Compassion in Action,” healthcare policy author and insurance expert Gregory Gallivan argues that insurance is in desperate need of reform. His proposed fix is an à la carte insurance model that lets consumers choose and pay only for the coverage they need.
“Affordable health care with total customization is a necessity for everyone,” Gallivan writes. “Customization is the only mechanism that will make coverage workable again.”
Healthcare Payment Reform That Allows Consumers To Pay Less While Insurers And Pharmaceutical Companies Still Prosper
Most payment-reform conversations in America start with lines already drawn. They make bold and adversarial demands to reduce insurer profits or restrain pharmaceutical pricing.
Gallivan’s pitch is different. It harnesses competitive, market-based incentives instead of fighting them.
His à la carte model is designed with tiers and optional riders that consumers can mix and match. For example, a young single adult might prioritize catastrophic coverage and an affordable pharmacy program. A growing family might add maternity coverage and pediatric care. Someone managing chronic disease might choose richer drug coverage and physical therapy as a standard feature.
“Consumers would spend less overall because they are no longer paying for benefits that go unused,” Gallivan explains. “Insurers and pharmaceutical companies would still win financially through scale and expanded participation.”
He points to the rule of large numbers. This is the idea that a broader risk pool and more insured people can support strong returns even with lower per-member costs.
“Increased competition could also pressure premiums downward,” Gallivan adds. “This is especially true if insurers are allowed to compete across state lines. It would be similar to the way prices tighten when multiple gas stations sit at the same intersection.”
At the same time, Gallivan does not pretend drug makers disappear from the equation. Instead, he redesigns how customers access drug coverage to make it more transparent and predictable.
“Formularies should be clearer year to year so patients can plan,” he explains. “Tiered right-to-try options without caps at the upper end can serve as a premium market segment. Such a structure could increase pharma’s revenue while giving patients a more direct path to advanced therapies.”
The proposal is unabashedly pro-consumer choice combined with a belief that insurers can profit from efficiency gains. For examples of these, Gallivan points to the use of AI to reduce fraud and eliminate redundant administrative structures that drive costs without improving outcomes.
How The ACA Subsidy Expiration And Rising Uninsured Rates Prove The Need For An À La Carte Insurance Model
The timing of Gallivan’s argument is no accident. Consumers are already living through higher prices across the economy, and healthcare premiums and out-of-pocket costs are among the most destabilizing. Many households have also felt the effects of the enhanced Affordable Care Act subsidies expiring at the end of 2025, and Gallivan argues that the moment calls for reform.
Gallivan argues that an à la carte approach better fits modern work. He points to workers who are stuck below the threshold for employer-sponsored benefits. Through no fault of their own, many are scheduled for 30 hours instead of full-time. Many in this situation struggle to afford coverage.
Gallivan’s critique is also about what coverage fails to do when people leave their home market. He highlights how out-of-network exposure can more than double when families travel, even within regions where state lines are a short drive apart.
“A family might easily get hit by an unexpected emergency after crossing state borders for a weekend trip,” Gallivan notes. “Many in this stressful time learn too late that their out-of-pocket maximum is dramatically higher out of market. For example, a $20,000 in-network maximum can explode into a $50,000 out-of-network bill for the same event. Under that framework, insurance becomes less like protection and more like a geographic restriction. Competitive and portable options can function nationally while still recognizing state-by-state rules.”
An Expert Author With A Practical Service Plan That Avoids Partisan Politics
Healthcare reform is crowded with loud voices. Many of them are partisan, and many of them are far removed from what ordinary consumers face when they try to buy a plan.
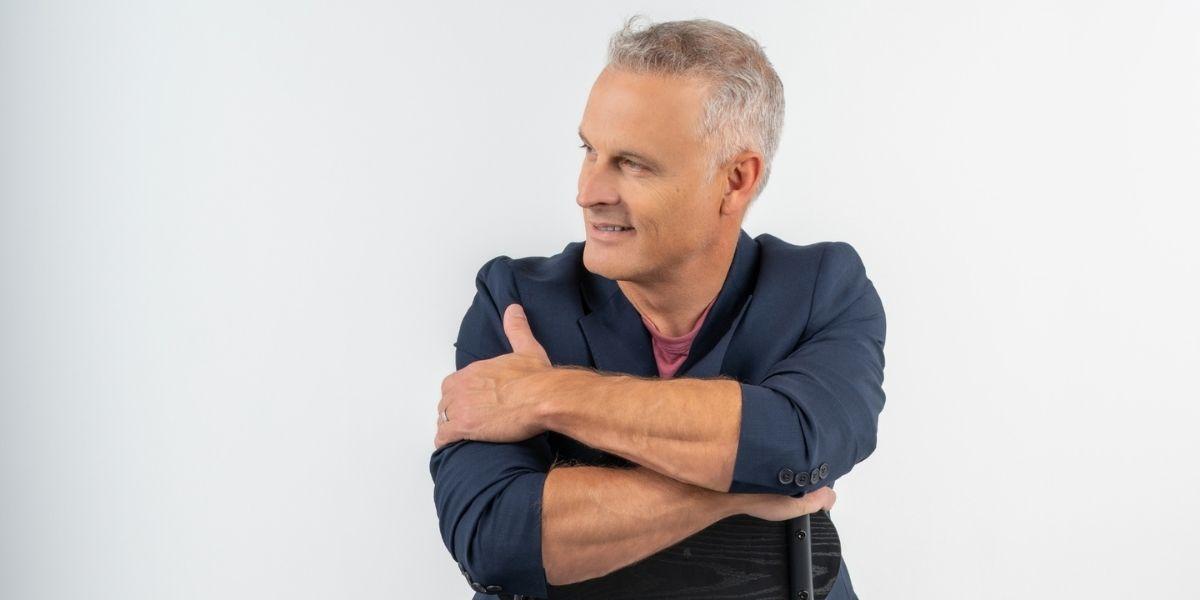
Gallivan’s credibility is rooted in pre-medical training paired with several years as a licensed health insurance broker. That background is reflected in his book’s tone. He has seen up close the gap between what policies promise and how they perform when someone gets sick or travels. He has worked with clients as they age or try to manage a chronic condition.
He also frames reform in terms of family and dignity rather than political tribe. “Family is the cornerstone that gives shape to our existence,” Gallivan writes. “Family first, always, no matter what.”
In his model, family plans do not mean forcing everyone into the same benefits. They mean designing coverage so that each member is appropriately covered without the household paying for unnecessary layers.
Gallivan is equally explicit about protecting people with preexisting conditions. “There will be no denial of insurance for preexisting conditions,” he writes. “All means all.”
That insistence on universality without turning the proposal into a scorched-earth fight may be the most intriguing part of his pitch. He calls the insurance redesign a “hearthstone,” or the first domino that makes other improvements to the nation’s struggling healthcare system possible.
In a moment when Americans are skeptical that big systems will ever feel personal again, Gallivan’s à la carte model attempts to rebuild the insurance model around what a person actually needs.
Disclaimer: This article is for general informational purposes only and does not constitute medical, legal, financial, or insurance advice. Coverage, costs, and eligibility vary by plan and individual circumstances. Consult a qualified professional before making health coverage decisions.